Sensex Rebounds 879 Points; Nifty Closes Above 22,500 | PMR Pulse, 9 October 2026
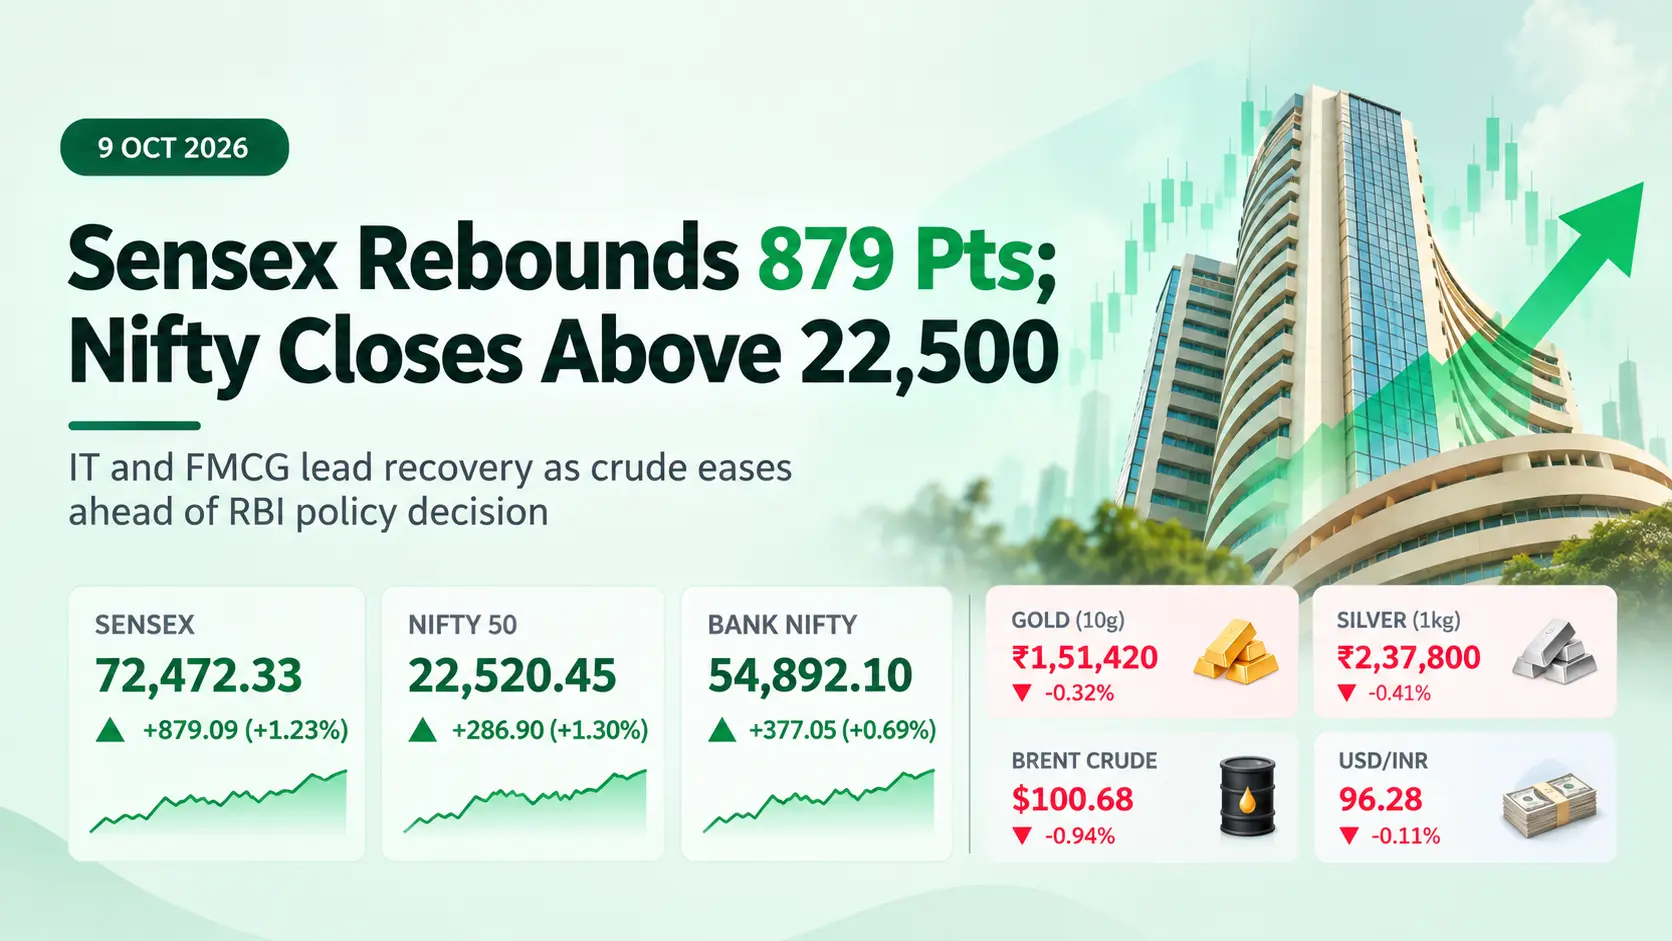
Today’s Overview: Indian equities rebounded on Friday after Thursday’s steep sell-off. The Sensex gained 879.09 points (1.23%) to 72,472.33 and the Nifty 50 added 288.65 points (1.30%) to 22,520.45, led by IT and FMCG shares. Oil eased after US President Donald Trump said there would be no attack on Iran before the US midterm elections, helping reduce immediate supply-disruption fears. The RBI, however, announced further liquidity-draining steps: a ₹25,000-crore bond sale and higher daily CRR maintenance from 16 October. Gold also rose as oil eased and the dollar softened. Market data below is based on sources available by publication
Today’s Top Finance, Economy & Money Stories
1. Market Rebound: Sensex Gains 879 Points, Nifty Moves Back Above 22,500
What happened: The Sensex closed at 72,472.33, up 879.09 points (1.23%). The Nifty 50 rose 288.65 points (1.30%) to 22,520.45. Midcap and smallcap indices also advanced, with the Nifty Midcap 100 up 1.56% and Nifty Smallcap 100 up 0.54%.
Why it matters: The rebound followed the prior session’s sharp sell-off and came as crude prices eased and global risk sentiment improved. However, a one-day bounce does not by itself confirm that volatility or foreign selling has ended.
PMR Insight: Avoid treating a rebound as proof that the correction is over. Track earnings, crude, the rupee, liquidity and market breadth together.
2. RBI Announces ₹25,000-Crore Bond Sale and Tighter Daily CRR Maintenance
What happened: The RBI said it would sell ₹250 billion (₹25,000 crore) of government bonds through open-market operations on Tuesday. From 16 October, banks must maintain 99% of the required cash reserve ratio daily, up from 90%.
Why it matters: These steps withdraw surplus liquidity from the banking system after the recent repo-rate increase. Tighter liquidity can put pressure on bond prices and influence short-term funding costs, even when individual banks do not immediately change every loan or deposit rate.
Who is affected: Banks, bond investors, money-market participants and borrowers whose rates reset according to lenders’ benchmarks. The eventual effect on retail loan rates depends on each lender’s funding mix and pricing decisions.
PMR Insight: A policy rate is only one part of monetary conditions. Liquidity operations and CRR rules also matter for the cost and availability of funds.
3. Oil Eases After Trump Comments on Iran; Gold Moves Higher
What happened: Brent crude fell more than 1% and traded below $103 per barrel after Trump said the US would not attack Iran before the midterm elections, easing immediate fears of a supply disruption. International spot gold rose more than 1% to around $4,182.59 per ounce in Friday trading; silver also gained.
Sector impact: Lower crude can offer relief to airlines, logistics, paints, tyres and other oil-sensitive businesses. Upstream oil producers may face the opposite price effect. Gold may benefit from a softer dollar and changing rate expectations, but it remains volatile.
Consumer impact: A fall in global crude does not automatically mean an immediate reduction in petrol, diesel, LPG or airfares. Domestic prices depend on taxes, inventory, currency movements and company pricing decisions.
PMR Insight: Treat geopolitical headlines as catalysts, not guarantees. Watch whether oil’s decline persists and whether shipping and supply risks actually ease.
4. ITC and TCS Lead the Rebound; IT Stocks Recover
What happened: ITC rose 5.08% to ₹266.95 and TCS gained 4.71% to ₹2,173. Adani Ports rose 3.49%, while Infosys gained 3.20% and HCL Technologies advanced 3.15%. Reliance Industries and Eternal were among the notable laggards.
What to watch: The TCS move follows its Q2 FY27 results, which reported revenue of $7.642 billion and annualised AI revenue of $3.1 billion. Investors will look for evidence that AI demand converts into sustained growth while margins hold up. IT exporters may also be influenced by currency movements and global technology spending.
Potential risk: A strong share-price reaction does not remove risks from muted sequential growth, margin pressure or uncertainty in client spending. FMCG performance also depends on input costs, volumes and consumer demand.
PMR Insight: Separate the day’s price move from the underlying business outlook. Earnings quality, guidance and valuations matter beyond a single session.
5. GST Process Reforms: Working-Capital Benefits, but Wait for Notifications
What happened: The GST Council’s latest reform package focuses on input tax credit, refunds, registration and compliance. Reporting highlights expanded ITC relief in selected areas, including employee insurance and certain infrastructure inputs, along with efforts to make refunds and compliance more efficient.
Business impact: If implemented as reported, faster refunds and broader eligible credits could improve working capital for some businesses. The effect will differ by industry and by the final legal notifications.
Important caveat: Businesses should not change tax treatment solely on the basis of headlines. Confirm the notified rules, effective dates and eligibility conditions with official GST guidance or a qualified tax adviser.
PMR Insight: These are primarily process and tax-credit changes, not a blanket GST rate cut for consumers.
6. Foreign Selling Remains a Risk Even as Domestic Stocks Recover
What happened: Market coverage reported continued foreign institutional selling, including large outflows in the latest reported session. Domestic institutions and retail participation can cushion declines, but they do not eliminate global-flow risks.
Why it matters: Foreign investors compare Indian returns with US yields, currency hedging costs and opportunities elsewhere. A weaker rupee can reduce dollar-based returns and make hedging more expensive.
PMR Insight: Daily FII/DII data is a useful context signal, not a standalone buy or sell trigger.
7. Your Money: What Today’s Developments Could Mean
- Investors: A rebound can be encouraging, but avoid chasing sharp moves without a plan. Review asset allocation and time horizon.
- Borrowers: RBI liquidity tightening may affect funding conditions over time. Check lender notices rather than assuming an immediate EMI change.
- Savers: Deposit-rate changes are bank-specific. Compare effective annual yield, tenure, premature-withdrawal terms and deposit insurance limits.
- Households: Easing crude is not an instant promise of lower fuel or travel costs. Track official domestic prices.
- Gold buyers: Global prices rose, but local prices also reflect USD/INR, import costs, duties and retail premiums.
Today’s Visual Dashboard
Airlines, logistics, paints may benefit
Funding and bond yields in focus
Watch earnings and client demand
Local prices also depend on FX
Detailed Market Snapshot
- Sensex: 72,472.33, up 879.09 points (+1.23%).
- Nifty 50: 22,520.45, up 288.65 points (+1.30%).
- Nifty Midcap 100: 58,787.30 (+1.56%).
- Nifty Smallcap 100: 19,153.70 (+0.54%).
- ITC: ₹266.95 (+5.08%).
- TCS: ₹2,173 (+4.71%).
- Brent crude: below $103/bbl in Friday trade after easing more than 1%; intraday quote, not a final settlement price.
- Gold: global spot around $4,182.59/oz, up more than 1% intraday; local Indian retail/MCX price differs.
- USD/INR: latest widely reported close was ₹96.88 on 8 October; a verified 9 October closing quote was not available in the sources checked.
Finance Word of the Day: Cash Reserve Ratio (CRR)
Meaning: The share of a bank’s net demand and time liabilities it must keep as cash with the RBI. CRR balances do not earn interest for banks.
Why it matters today: The RBI’s move to require banks to maintain 99% of the required CRR daily, from 90%, can reduce banks’ flexibility to manage short-term liquidity.
Investor Lesson: Don’t Confuse a Rebound With a Trend Change
A sharp recovery after a sell-off can reflect short-covering, relief on one macro headline or bargain hunting. A more durable recovery needs confirmation from earnings, market breadth, foreign flows, currency stability and energy prices. Match decisions to your time horizon and risk tolerance.
Tomorrow’s Market & Economy Watch
- RBI liquidity operation: Track bond-market reaction and short-term money-market rates ahead of Tuesday’s announced OMO bond sale.
- Oil and geopolitics: Watch whether Brent stays below $103 and whether shipping-risk concerns continue to ease.
- Foreign flows: Check the latest FII/DII data and currency-hedging costs.
- Q2 earnings: Watch upcoming company results for revenue growth, margins and management guidance.
- Gold and dollar: Monitor US yields, the dollar and geopolitical headlines for direction.
Plan Your Financial Strategy with PlanMyReturns Tools
Today’s stories point to market volatility, rate uncertainty, oil-price swings and gold strength. Use the tools most relevant to your own plan:
- SIP Calculator: Model disciplined long-term investing through volatility.
- Lumpsum Calculator: Compare one-time investment scenarios.
- Home Loan EMI Calculator: Estimate EMI impact if your lender revises rates.
- Loan Prepayment Calculator: Compare interest savings from prepayment.
- FD Calculator: Estimate maturity values across deposit tenures.
- Gold Investment Calculator: Compare gold allocation scenarios.
- Inflation Calculator: Understand the effect of changing prices on future goals.
About PMR Pulse
PMR Pulse is PlanMyReturns’ daily finance, economy and market briefing. We explain what changed, why it matters, which sectors may be affected and what investors, borrowers, savers and households should watch next.
Published: 9 October 2026, 7:30 PM IST. Market values reflect latest source data available at publication.