You received your Diwali bonus. Now you face the classic middle-class dilemma: do you hand it over to your bank to reduce your home loan, or do you put it into a mutual fund? Here is the exact math to help you decide.
Every October, thousands of salaried professionals receive a festive bonus of ₹1 lakh to ₹5 lakh. For those carrying the heavy weight of a 20-year home loan, the first instinct is often to log into their banking app and prepay a chunk of the principal. Getting out of debt simply feels good.
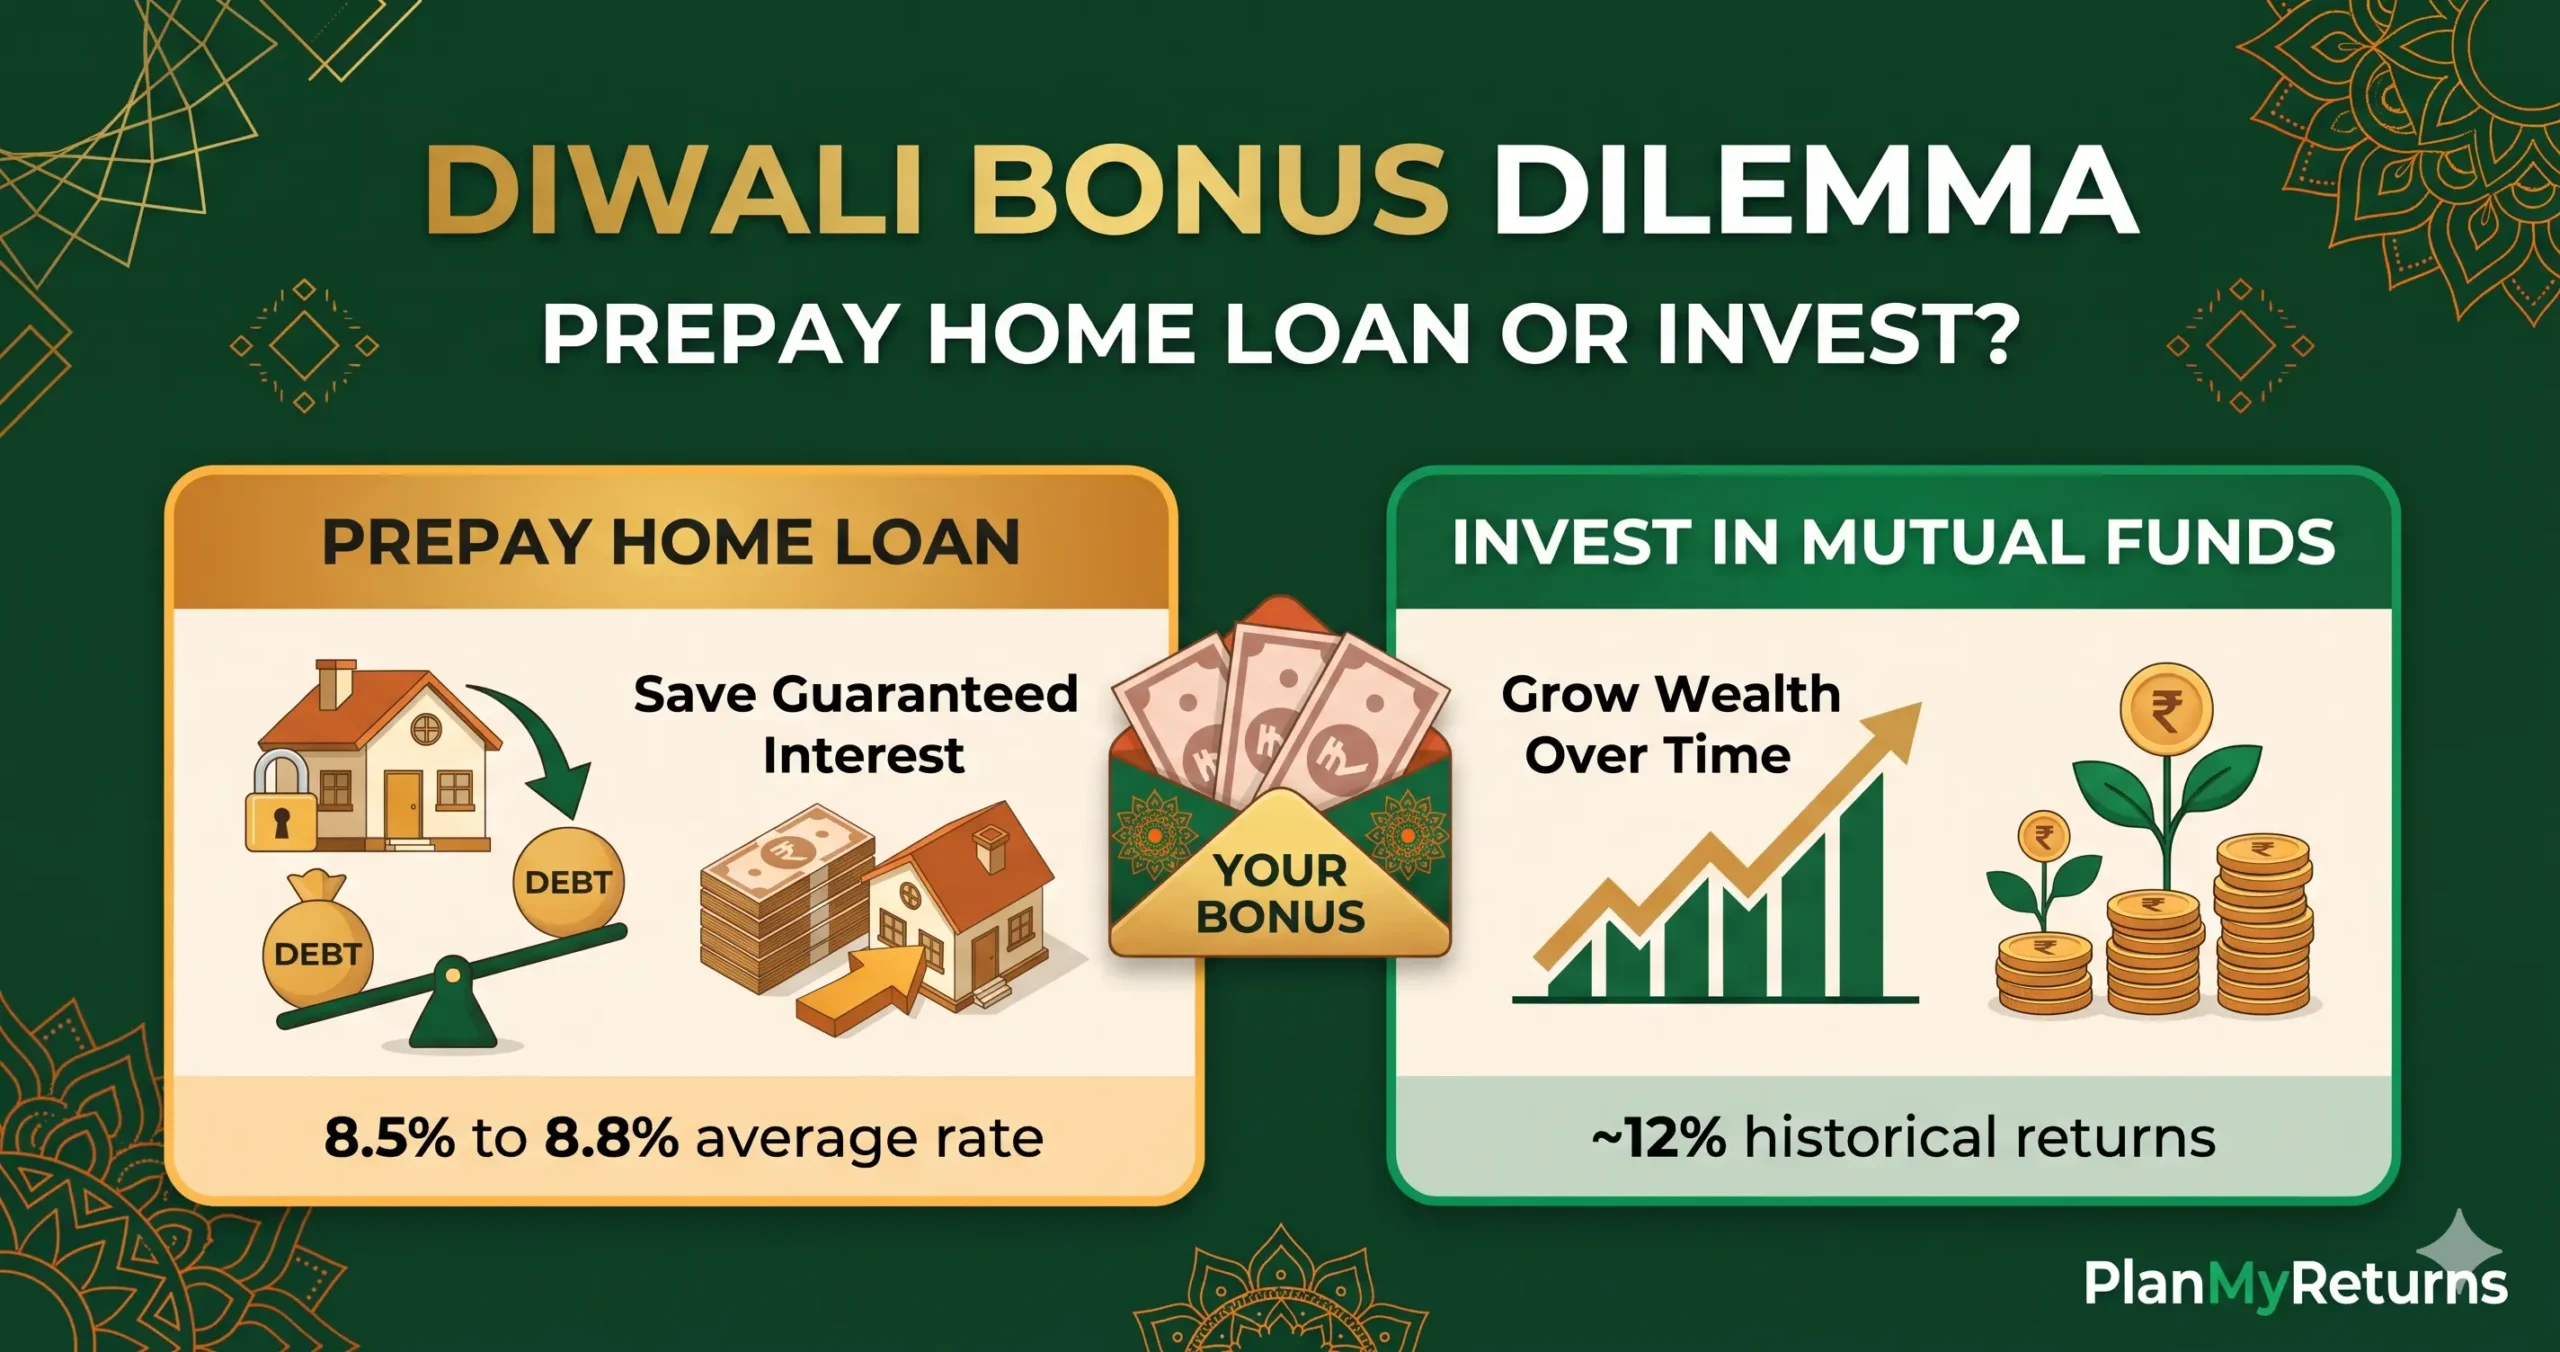
But feelings do not create wealth. Math creates wealth. Right now, banks like SBI and HDFC are charging around 8.5% on a standard floating-rate home loan. Meanwhile, a basic Nifty 50 index fund has historically delivered around 12% over the long term.
Should you grab the guaranteed 8.5% savings, or chase the 12% market return? We will break down both sides of the coin and show you exactly what your bonus is worth in each scenario.
Short Answer: If you expect your mutual fund to generate a higher return than your home loan interest rate, investing creates more total wealth. However, prepaying your loan offers a 100% guaranteed, tax-free return equal to your loan’s interest rate. If you are a conservative investor, prepaying is the safest choice.
The Case for Prepaying Your Home Loan
Prepaying your home loan is exactly like earning a guaranteed, risk-free return equal to your loan’s interest rate. If your home loan costs you 8.5% a year, prepaying ₹2 lakh saves you from paying 8.5% interest on that money for the rest of your loan tenure.
The Return is 100% Guaranteed
Stock markets go up and down. A mutual fund might give you 15% one year and minus 5% the next. But when you prepay your home loan, your bank is legally forced to stop charging you interest on that amount. The savings are locked in forever.
The Savings Are Completely Tax-Free
When you earn profits in a mutual fund, you have to pay Long-Term Capital Gains (LTCG) tax of 12.5% when you withdraw. The interest you save by prepaying a loan is not taxed by anyone. A penny saved is truly a penny earned.
The Golden Rule of Prepayment: When you prepay, your bank will ask if you want to lower your monthly EMI or reduce your loan tenure. Always ask to reduce your loan tenure. Keeping your EMI the same while paying off the principal faster is the secret to getting out of debt years early. You can verify this using our Home Loan EMI Calculator.
The Case for Investing the Bonus
If prepaying is so safe, why do financial planners often tell you to invest the money instead? Because your home loan is actually the cheapest money you will ever borrow.
If you can borrow money from a bank at 8.5% and invest it somewhere that pays you 12%, you are making a 3.5% profit on the spread. Over 10 or 15 years, that difference compounds into a massive amount of wealth.
The Power of Compounding
If you put ₹2 lakh into an equity mutual fund earning 12%, it doubles every six years. While a home loan strictly costs you simple interest on a reducing balance, an equity investment gives you interest on top of your interest.
You Keep Your Money Liquid
Once you give ₹2 lakh to your bank for prepayment, that money is gone. You cannot ask for it back if a medical emergency hits next month. If you put that same money into an open-ended mutual fund, you can withdraw it to your bank account within three days.
The Hidden Tax Trap You Must Check
Before you rush to prepay, you must check your tax return. If you use the Old Tax Regime, the government allows you to claim a deduction of up to ₹2 lakh on your home loan interest under Section 24(b).
If you prepay a large chunk of your loan, your future interest payments will drop. If your annual interest drops below the ₹2 lakh limit, you will lose part of your tax deduction, causing your income tax to go up next year. Use our Income Tax Calculator to check exactly where your current deductions stand.
Prepay vs. Invest Bonus Calculator
Enter your Diwali bonus amount and loan details to see which option creates more wealth.
This calculator compares the opportunity cost of a lump sum over the remaining loan tenure. It assumes constant returns and rates for simplicity, and does not factor in LTCG taxes or Section 24(b) benefits.
Want more detail? Open the full Prepay vs Investing Calculator →
The Middle Path: The 50/50 Strategy
You do not have to choose just one path. If you are stuck between the logic of investing and the emotional comfort of being debt-free, split your bonus down the middle.
By splitting the amount, you protect yourself against market crashes while still shrinking your monthly financial burden. Whatever you choose, do it quickly. A bonus sitting idly in a savings account earning 3% is the only guaranteed way to lose money to inflation.
Ready to test the math on your exact monthly EMI? Plug your loan details into our detailed tool to see exactly which month your loan will finish if you prepay today.
Open The Loan Prepayment CalculatorShould I use my Diwali bonus to prepay my home loan?
If your home loan interest rate is higher than what you can earn from a safe investment, you should prepay. However, if you expect mutual funds to give you 12% and your home loan is at 8.5%, investing the bonus will create more wealth over time.
Does prepaying a home loan reduce my tax benefits?
Yes. If you claim the Section 24(b) deduction for home loan interest, prepaying the loan reduces your outstanding principal. This lowers your future interest payments, which means your tax deduction might also drop.
Is it better to reduce my EMI or my loan tenure when I prepay?
Always ask your bank to reduce the loan tenure. Keeping your EMI the same but shortening the years saves you a massive amount of interest in the long run.